
Company Startup Loan: How New Business Owners Actually Get Funded (When Banks Say No)

Company Startup Loan: How New Business Owners Actually Get Funded (When Banks Say No)
Most people searching for a company startup loan have already been told "no" at least once. The bank wanted two years of tax returns you don't have, revenue you haven't earned yet, and a crystal ball showing future profits. Here's what actually works when you're starting from scratch.
What Is a Company Startup Loan and Why It's So Hard to Get?
A startup business loan is any form of debt financing used to launch or grow a brand new business. That includes real estate investing, franchises, online businesses, brick and mortar shops, or business acquisitions. If the company is pre-revenue or under two years old, it falls into this bucket.
Why Lenders Treat Startups Like a Risk
Banks and traditional lenders see new businesses the same way most of us see a stranger asking to borrow our car. There's no track record. No proof you'll bring it back in one piece. Many lenders require two or more years in business and strong revenue before they'll even open your application. Personal credit scores are crucial for startup loan applications, and a good credit score typically starts at 650 for most loans. A good credit score can help qualify for better loan terms across the board.
Funding the Owner vs Funding the Business
Here's where it gets interesting. When your new business has zero revenue, lenders shift their focus entirely to you, the owner. Your personal credit history, your income, your assets. True business funding, the kind based on company revenue and cash flow, usually requires at least two years in operation and roughly $20,000 or more per month in revenue. Until then, you're working with tools tied to personal finances.
Think about it in real numbers. You need $50,000 for equipment, $30,000 for rehab on a property, $20,000 for working capital. That's $100,000 in startup costs, and no lender is handing that to a brand new LLC with a business plan and a dream.
Company Startup Loan Options: From Traditional Lenders to Creative Capital
Diverse funding options cater to different borrower needs and circumstances. Here's a quick comparison of what's actually out there.
SBA loans can reach up to $5 million under the 7(a) programme, but typically need 2+ years in business and strong owner credit. Microloans can provide up to $50,000 for startups through intermediary programmes, with average microloans around $13,000. The Colorado Startup Loan Fund, for example, offers loans from $500 to $150,000 for qualifying entrepreneurs. Bank loans favour existing businesses with verifiable revenue. Equipment loans use the purchased equipment as collateral, making them more accessible even for younger companies. Business credit cards are easier to obtain than traditional loans, and when stacked strategically, can yield $50,000 to $100,000 in combined limits. Online business lenders may offer quicker approvals than traditional banks, though often at higher cost. Personal loans can fund a startup when corporate credit history is lacking.
Interest rates and fees are critical factors in total loan cost calculations, and comparison of total loan costs is essential before choosing financing options. Lenders may have unique eligibility requirements depending on their programme.
Most startup founders don't rely on one product. They stack multiple solutions: business credit cards for immediate expenses, a personal term loan for the down payment, maybe a small equipment loan. Gap Funded specialises in assembling these pieces into a coherent capital stack rather than competing with banks or SBA loans.
Traditional Small Business Loans and SBA Loans: When They Work and When They Don't
SBA 7(a) loans are the most widely used loan programme, designed for various business purposes including working capital, equipment purchase, and commercial real estate. The 504 programme targets large fixed asset purchases, while SBA microloans can provide up to $50,000 through third party intermediaries.
Common eligibility requirements include 2+ years in business, verifiable income, owner credit scores of 680 or higher, clean history with no recent bankruptcies, and enough cash flow to service debt. Businesses must meet SBA size standards for loans. Collateral requirements vary depending on the loan type and lender, and startup loan applications may require personal guarantees from borrowers. Traditional banks often require a solid business plan before lending, and comprehensive cash flow projections are important for loan approval.
Many lenders require two years of business history for funding. Technical assistance may be required for some startup loans, particularly for businesses under 24 months of revenue history. Some lenders require technical assistance programmes to provide education and guidance before approving funding.
The trade off? Lower interest rates and longer, more flexible terms. But the application process can take 30 to 90 days, documentation is heavy, and if your deal is time sensitive, that timeline kills it. Gap Funded is not an SBA lender, but we can help founders use gap funding to reach the point where SBA loans and traditional business lines become available later.
Alternative Startup Funding: Equity, Grants, Crowdfunding and Bootstrapping
Not all startup funding comes as loans. Equity financing involves raising money from investors in exchange for ownership in your own business. Angel investors or friends and family might provide $50,000 to $250,000, but they expect equity splits, influence over development, and often returns within 3 to 7 years. Venture capital rarely applies to real estate or small businesses unless the model is highly scalable.
Grants are competitive but available for minority owned startups, clean energy, tech, and other specific industries. They're non repayable, which is brilliant, but the application process is slow and bureaucratic. Rarely fast enough to close a real estate deal.
Crowdfunding platforms like Kickstarter help raise startup funds through rewards based campaigns. You might raise $40,000 from a broad audience, but it takes months of marketing effort with uncertain success. Equity crowdfunding adds regulatory compliance on top.
Bootstrapping works best for low overhead digital or service businesses. If you need $200,000 in investment capital for a rehab, waiting for client revenue to trickle in won't get the property purchased.
Using Personal Finances for a Startup: Risks, Rewards, and Safer Structures
Here's the honest reality. Most true startup business loans are actually based on personal credit and income. Savings, 401(k) rollovers, home equity, personal term loans used for business, and personal credit cards. Only about 12% of startups use an actual business loan for their initial capital. The majority rely on personal funds and personal finances.
The risk is real. If your new business fails, the debt remains yours. Your personal credit takes the hit. Mixing business and personal accounts creates tax headaches and makes future financing harder to access.
Safer structures exist. Form an LLC, get an EIN, open a dedicated business bank account from day one. Document every owner contribution. Set defined caps on personal exposure per deal. Monitor your credit report regularly to maintain good credit history and reduce identity theft risk.
Gap Funded's approach to credit based funding, including unsecured personal term loans and structured business credit card stacking, helps you use strong personal credit strategically instead of haphazardly maxing out random cards.
Where Most Founders Get Stuck: The Funding Gap Between Lender Approval and Real Startup Costs
Picture this. An investor gets approved for a $250,000 hard money loan on a property. Sounds great. But the deal still needs $60,000 for the down payment, $25,000 in closing costs and fees, $45,000 for rehab before lender draws kick in, plus six months of holding costs. That's another $130,000 that the primary lender won't cover.
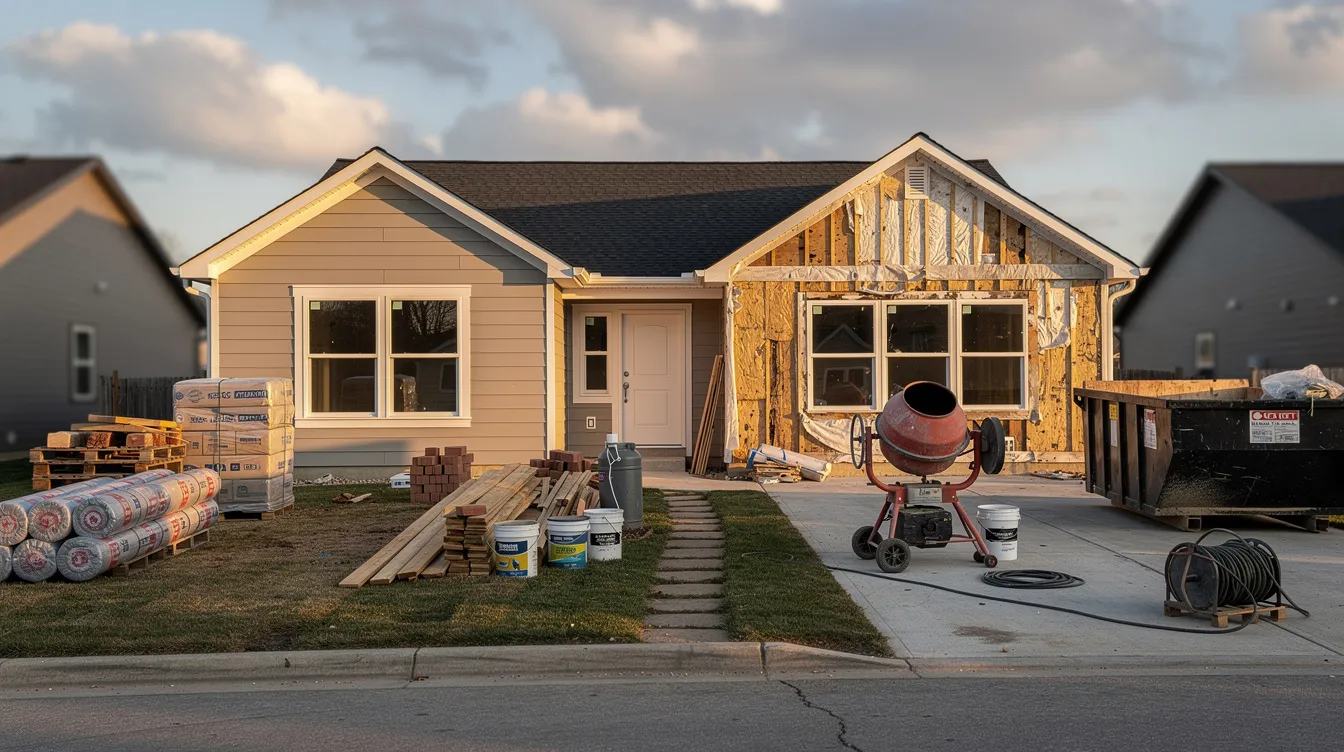
The most common funding gaps for entrepreneurs include down payments, earnest money deposits, closing costs, rehab or build out, furniture and equipment, inventory, marketing launch, payroll buffer, and working capital. Traditional business loans and SBA loans rarely cover 100% of a project cost, especially for fix and flip deals, BRRRR strategy properties, short term rentals, or construction development.
This "last mile" capital is where many good deals die. Not because the owner has bad credit or a weak deal, but because they can't document enough liquid cash to bridge the gap between what the lender funds and what the project actually costs.
How Gap Funded Structures Startup Capital Stacks (Without Equity Splits)
Gap Funded acts as a funding intermediary focused on non dilutive capital for real estate investors and small business owners. We don't compete with your primary lender. We fill the gap between what they fund and what you actually need. The concept is capital stacking: layering multiple tools rather than hunting for one magical startup business loan.
Here's the recommended order, and sequencing matters because applying out of order can knock out later approvals.
First, unsecured gap funding and debt consolidation to free up capacity and cover immediate cash needs like down payments and earnest money. Qualification typically starts at FICO 650+. Second, 0% intro APR credit card stacking for flexible expenses like materials, marketing, and holding costs. Third, asset based capital like a HELOC on investment property (use the HELOC calculator to estimate), plus hard money or DSCR loans for larger real estate projects. Fourth, once you hit 6 to 24 months of history and $15,000 to $20,000 per month in revenue, you can access business lines of credit, business term loans, or a merchant cash advance. Flexible lines of credit help manage unexpected operational expenses once revenue is flowing. Business lines of credit can provide quick access to cash for small businesses at that stage.
Key advantages: soft credit pulls to check options, no equity splits, no liens on the deal property, and rapid gap funding designed to work alongside your primary lender and partners.
If you've got a deal or a startup plan ready, complete the quick application for a funding review.
Step by Step: How to Qualify and Apply for a Company Startup Loan with Gap FundedStep by Step: How to Qualify and Apply for a Company Startup Loan with Gap Funded
You don't need two years in business. But you do need decent personal credit (aim for 650+), verifiable income or assets, and a clear plan for how you'll use and repay the funds.
Pre application checklist: Pull and review your personal credit reports for accuracy and identity theft issues. Gather proof of income (W-2s, pay stubs, tax returns) and any existing business revenue statements. Prepare a basic deal summary or business plan with specific numbers: purchase price, rehab budget, ARV, expected revenue, exit strategy. Having a well prepared business plan improves loan approval chances significantly, and a complete application package can speed up loan approval.
The process: Complete the short online form at gapfunded.com/apply. No hard credit pull at this stage. Submit requested documents so the team can match you with the right unsecured, asset based, and revenue based options. Review your personalised capital stack proposal with estimated limits, terms, and how each product fits your specific gaps.
Time to funding can range significantly between lenders. Initial feedback typically comes within 24 to 72 hours. Credit card stacking can be approved same day. HELOCs take longer depending on appraisal and title work.
The goal is long term success: use early rounds of funding to execute deals, establish cash flow, then graduate to larger resources like SBA loans or bank business loans once your company meets standard criteria.
Protecting Your Credit and Business Future While You Borrow
Every startup business loan or credit product affects either personal or business credit. Treat borrowing decisions as strategic, not desperate.
Target healthy debt service ratios where deal revenue covers payments by at least 1.25x. Set maximum total exposure vs expected profit. Plan full payoff dates, especially before 0% APR ends on stacked credit cards. Monitoring your credit report helps maintain good credit history over time.
Protect against fraud and identity theft when seeking funding online. Verify lender legitimacy, watch for advance fee scams, and use secure document portals. Open dedicated business bank accounts, use your EIN where appropriate, and clearly track business expenses for tax and loan underwriting purposes.
I reckon the smartest thing any new business owner can do is treat early capital as a bridge, not a destination. Build credit, build revenue, and the better tools open up. We're here to help you get across that bridge without giving up ownership or control. Start with a no obligation funding review and see what you qualify for today.
Related Reading
This article is for educational purposes only and isn't financial, legal, tax, or investment advice. Credit and financing outcomes depend on your own situation. Talk to a licensed financial professional before making funding decisions for your business.