
Capital Stack in Real Estate: Definition, Priority, and Practical Funding Solutions

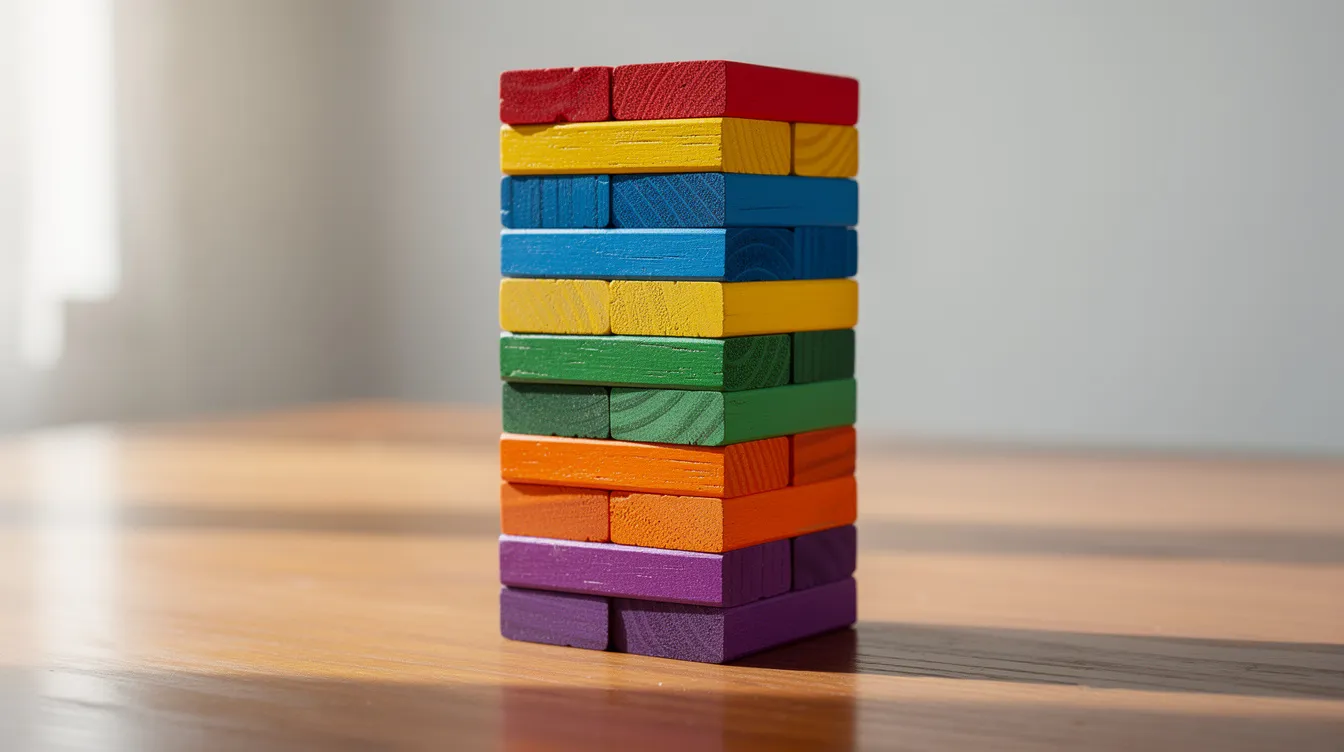
Most real estate deals don't die because the property was bad. They die because someone couldn't figure out how to fund the last 20 to 30 percent of the total capital needed. That shortfall sits somewhere in the capital stack, and if you don't understand where, you're flying blind.
Capital Stack Definition and Why It Matters
Here's the capital stack definition in plain English: it's the layered hierarchy of all the capital used to fund a real estate project, ordered by who gets paid first and who takes losses first. Capital stacking refers to the hierarchy of various funding sources for projects, from the safest money at the bottom (senior debt) up through mezzanine debt, preferred equity, and common equity at the top.
The stack isn't about how much money is in the deal. It's about payment priority, risk, and who's left holding the bag when things go sideways. Each layer in a capital stack has a distinct claim on cash flow and varies in risk.
Why should you care? A few reasons:
- It determines whether your deal is even fundable. A $5M apartment building might need $3.5M in senior debt and $1.5M from equity. If you can't fill that equity layer, the deal dies on the vine.
- It dictates your risk profile. Where you sit in the stack matters more than how much you put in.
- It affects returns. Investors in lower layers of the stack accept lower yields in exchange for security. Those at the top take the most risk but capture the potential upside.
- It shapes control. Lenders set covenants. Preferred shareholders may have blocking rights. Common equity holders run the show but eat losses first.
Capital stacking allows businesses to maximise leverage by combining different types of financing. Whether you're buying a $2M short term rental portfolio or a 100 unit apartment complex, understanding the stack is step one.
Capital Stack vs. Capital Structure: What's the Difference?
People use these terms interchangeably, and it trips them up. Capital structure describes the makeup of financing: how much is debt versus equity. The capital stack describes who gets paid, in what order, and who absorbs losses. Capital structure decisions impact financial leverage and ownership distribution, but the stack shows you the pecking order.
Here's how they differ on the same deal:
- Deal price: $10M
- Capital structure view: 70% debt ($7M) and 30% equity ($3M). Simple ratio.
- Capital stack view: $7M senior debt sits at the bottom with first claim. Above that, $1M mezzanine debt. Then $1M preferred equity. Then $1M common equity at the top.
Both views describe the same $10M, but the stack tells you something the structure doesn't: that $1M in common equity and $1M in preferred equity carry very different risk, even though they're both "equity." Confusing the two leads to thinking all 30% equity is equal risk, when the preferred equity investors receive returns before common equity holders.
This distinction matters beyond real estate too. A typical early stage SaaS company might have 10% debt and 90% equity, while mature software companies may operate with 40% debt and 60% equity. Same concept, different ratios, same need to understand priority.
Layers of the Capital Stack in Commercial and Multifamily Real Estate
The capital stack includes senior debt, mezzanine debt, preferred equity, and common equity. Think of it as a building: the foundation is the most secure, and the penthouse has the best view but the longest fall.
In a typical 2024 to 2026 commercial real estate or multifamily real estate deal, the proportions look roughly like this (from bottom to top):
- Senior debt: 65 to 80% of asset value. First claim. Least risk, lower returns.
- Mezzanine debt: 5 to 15% of asset value. Subordinated to senior. Higher risk, higher return.
- Preferred equity: 5 to 15%. Priority over common equity but below all debt. Hybrid layer.
- Common equity: 10 to 30%. Residual ownership. Last paid, first to lose. The riskiest layer.
Not every deal uses all four. If you're doing a fix and flip with a hard money loan, your stack is probably just senior debt and common equity. Large commercial real estate developments are where you'll see the full four layer stack.
Senior Debt: Base of the Capital Stack
Senior debt is the primary commercial real estate loan secured by first lien on the property. It has the highest repayment priority and the lowest risk in the stack. Senior lenders, whether banks, agency lenders, or DSCR lenders, get paid before anyone else from property cash flow and from sale proceeds in a liquidation.
Senior debt typically covers 65% to 75% of a property's purchase price. In mid 2026, stabilised multifamily rates for well qualified borrowers sit in the 5.5% to 7.5% range depending on deal quality and LTV.
Concrete example: a $5.5M multifamily asset with a $4M senior loan at roughly 72% LTV, fixed interest at 6.5%, 30 year amortisation. The lender has collateral, a fixed repayment schedule, and first claim on everything.
Key characteristics:
- First lien position with foreclosure rights
- Fixed interest rates and principal amortisation
- Restrictive covenants (DSCR minimums of 1.20x to 1.30x are common)
- Lowest return among all layers
- Debt holders have contractual rights to repayment regardless of performance
That last point is critical. Institutional lenders and banks providing senior debt don't care if your deal is wildly profitable or barely breaking even. They get repaid first. But they rarely finance 100% of total project cost, which is exactly where the funding gap appears.
Mezzanine Debt: Filling the Gap Above Senior Debt
Mezzanine debt is subordinated debt financing that sits above senior debt but below equity in the capital stack. It exists because senior lenders won't fund the full cost, and someone needs to bridge that gap.
In a $10M real estate project where senior debt covers $7M, mezzanine financing might provide $1.5M, leaving $1.5M for equity funding. Mezzanine debt offers higher returns, typically 12% to 18% interest, reflecting the higher risk of being second in line.
Common mezzanine terms include:
- Higher interest rates than senior debt, sometimes with PIK (payment in kind) interest that accrues
- Collateral via UCC Article 9 pledge of the LLC's equity interests rather than a property lien
- Shorter maturities of 3 to 5 years
- Subordinate position to senior debt in all debt obligations
Higher debt increases potential returns but also risk. That's the mezzanine trade off in a nutshell.
For individual investors doing fix and flip, BRRRR, or short term rental deals, formal mezzanine debt is rarely available. The deal sizes are too small, and the paperwork is painful. Instead, smaller investors replicate the same gap filling role with personal term loans, stacked credit cards, or subordinate private loans. Different label, same function in your personal capital stack.
Preferred Equity: Priority Equity in the Middle of the Stack
Preferred equity is a hybrid layer positioned between mezzanine debt and common equity in the capital stack. It's equity, so it doesn't have foreclosure rights like debt. But it has priority over common equity in distributions.
Preferred equity investors receive returns before common equity holders. Typical preferred returns in today's market run 8% to 12% annually, sometimes with a participation kicker that gives them a slice of upside beyond their preference.
Realistic example: on a $10M apartment acquisition with $7M senior debt, $1M preferred equity carrying an 8% preferred return, and $2M common equity, the preferred equity investors get their distributions satisfied before a dollar flows to common equity investors.
Key features of preferred equity:
- Priority in distributions over common equity but subordinate to all debt
- Fixed or preferred return with limited upside beyond the preference
- No foreclosure rights, but may include GP removal or blocking rights as contractual remedies
- Preferred shareholders carry a different risk than common equity but more risk than debt holders
Most small and mid size investors won't directly issue preferred equity. But you might invest in syndications or funds structured this way. Understanding where preferred equity sits in the stack helps you evaluate what you're actually buying into when someone pitches you an "8% preferred return."
Common Equity: Highest Risk, Highest Reward Position
Common equity is the true ownership layer at the top of the capital stack. Common equity holders have the residual claim on cash flow and sale proceeds. They get paid last. They absorb losses first. Common equity is the riskiest layer in the capital stack, but it's also where serious wealth gets built.
Equity holders receive returns only after all debt obligations are satisfied. That's the deal.
Liquidation example: a $5M multifamily property financed with $3.5M senior debt and $1.5M total equity sells for only $3.6M in a downturn. The senior lender recovers nearly all principal. The common equity? Virtually wiped out.
Common equity is the riskiest position but offers the highest potential return through appreciation, value add improvements, and profit splits. This is why investors still favour it for long term real estate investment strategies like BRRRR, fix and flip, or short term rentals where forced appreciation can dramatically shift the numbers.
Common equity investors accept that they're last in line because, in the good scenarios, leverage works in their favour. When a property doubles in value, the lender still gets the same fixed interest. The equity investment captures the rest.
How the Capital Stack Works in Practice: Cash Flows, Defaults, and Bankruptcy
Cash flows follow a waterfall distribution based on the capital stack hierarchy. In a normal operating quarter, money flows like this:
- Rental revenue comes in
- Operating expenses get paid
- Senior debt service is covered first
- Mezzanine debt interest is paid next
- Preferred equity distributions follow
- Common equity gets whatever remains (the profits, or nothing)
Take a 100 unit multifamily real estate deal generating $600,000 annual NOI. Senior debt service runs $350,000. Mezzanine interest costs $80,000. Preferred equity return is $60,000. That leaves roughly $110,000 for common equity.
Now drop NOI by 20% to $480,000. Senior debt still gets its $350,000. Mezzanine might scrape by with reduced payment. Preferred equity and common equity? Probably nothing.
In a financial downturn, losses propagate from common equity to preferred equity and then to mezzanine debt. Losses in a capital stack typically hit junior capital layers first before affecting senior debt. In liquidation, senior debt holders are paid before equity holders, and losses are distributed from the top of the capital stack first.
Key lessons:
- Small drops in property value or cash flow disproportionately hammer common equity
- Payment priority isn't theoretical until a deal underperforms, then it's everything
- Assessing risk means understanding exactly where you sit in this waterfall
Analysing a Capital Stack: Ratios and Risk Checks
Lenders and investors use three main metrics to evaluate whether a capital stack is sound or overleveraged:
- LTV (Loan to Value) = Loan Amount / Property Value. Senior lenders typically cap this at 60% to 75% for most real estate transactions. Higher LTV means less equity cushion. Median LTV for DSCR investment property loans sits around 70%.
- DSCR (Debt Service Coverage Ratio) = NOI / Annual Debt Service. Most senior lenders require at least 1.20x to 1.30x. A DSCR of 1.0x means you're breaking even on debt payments with zero margin.
- Debt Yield = NOI / Loan Amount. This metric tells a lender what return they'd get if they had to take over the property. It's independent of property value swings, which makes it useful for assessing risk in volatile markets.
The structure of a capital stack affects repayment priority and risk exposure for investors. Higher financial leverage from capital stacking increases the risk of default if revenue falls. When DSCR drops below lender thresholds, you're in covenant violation territory.
These ratios tell you where senior debt stops and where you need to fill the remaining capital with equity or alternative financing sources.
Why the Capital Stack Matters to Real Estate Investors (and Where the Funding Gap Appears)
Understanding why the capital stack matters goes beyond theory. It shapes your risk tolerance, potential returns, control over the deal, and whether you can close at all.
The most common funding gaps for individual investors hit at predictable points:
- Down payment (senior debt covers 65% to 75% of property price, leaving 25% to 35% unfunded)
- Closing costs that lenders won't roll into the loan
- Rehab or renovation budget on fix and flip or BRRRR deals
- Earnest money deposits needed to lock up competitive deals
- Reserves and working capital during lease up or stabilisation
Capital stacking can bridge funding gaps that traditional lenders may not cover. Institutional investors fill these gaps with mezzanine debt or preferred equity. But most smaller investors don't want the complexity, the cost, or the equity dilution that comes with bringing in outside capital at those layers.
They want short term, non dilutive money that gets them across the finish line.
How Gap Funded Helps You Complete the Capital Stack Without Giving Up Equity
Gap Funded sits between your primary lender's loan and your total project cost. We're not a hard money lender. We're not a DSCR lender. We fill the gap between what those lenders fund and what you actually need to close, using tools that don't put a lien on your deal property.
Using capital stacking can preserve ownership for founders by reducing equity dilution. That's the whole point of what we do. The specific gaps we commonly cover include down payments, closing costs, rehab draws, earnest money deposits, reserves, and working capital.
Here are the tools, in the order that matters (applying out of sequence can knock out later approvals):
- Debt consolidation: clean up existing high interest obligations first to improve your credit profile and borrowing capacity
- Unsecured personal term loans via gap funding: larger amounts, fast access, ideal for down payments and rehab
- Business credit card stacking at 0% introductory APR: flexible use for materials, carrying costs, and short term needs
- HELOCs on existing property: tap equity you already have without touching the new deal's ownership
These tools function like your personal mezzanine capital in the stack. No equity splits. No preferred equity position given to an outside investor. No liens on the deal property.
Realistic qualification: typical FICO of 650 or higher, verifiable income or business revenue, or equity in existing property. Even newer businesses that haven't hit two years or $20K per month revenue can often qualify through personal credit based funding.
Choosing Your Position in the Capital Stack: Strategy for Different Investor Profiles
Where you sit in the capital stack should match your risk tolerance, experience, and goals:
- Risk averse investors prefer the debt side. Lending through debt funds, note investing, or senior positions. Lower risk, lower returns, less active involvement.
- Moderate investors use preferred equity or lower leverage common equity. They want some upside and some protection. A 65% LTV DSCR loan plus saved capital and a HELOC to cover the rest is a common setup.
- Growth focused operators take the common equity position. They accept the most risk for the potential returns from value add, forced appreciation, or short term rental income. A new investor using hard money plus gap funding to do a fix and flip with minimal personal capital is a classic example.
Gap Funded's solutions are built for that third group: investors and operators in the common equity position who need temporary, non dilutive capital to reach the equity threshold their primary lender requires. We help you fill the stack without diluting your ownership or giving someone else an equity claim on your deal.
Putting It All Together: Building a Safer, Fundable Capital Stack
Building a capital stack that actually closes and survives market stress comes down to a few principles:
- Start with conservative senior debt sized by realistic DSCR and LTV assumptions. Don't assume best case rents.
- Avoid stacking too much subordinate borrowing. If your total debt pushes DSCR below 1.20x, you're one bad quarter from trouble.
- Use non dilutive gap funding for specific needs (down payment, rehab, closing costs) rather than to cover ongoing operating losses.
- Stress test your exit. Model what happens to each layer of your stack if property value drops 10% or 20%. If common equity gets wiped out at a 10% dip, your stack is too aggressive.
Remember: the highest risk sits at the top of your stack. Common equity and any personally guaranteed financing are where you're most exposed. Understanding the risk return profile of every layer before you sign is what separates investors who build wealth from those who give it back.
If you've got a deal and a funding gap, we can probably help. The application is a soft pull, takes a few minutes, and won't impact your credit just to check your options.
Apply for a customised funding plan at gapfunded.com/apply
No equity splits. No liens on the deal property. Fast execution that matches your closing timeline, whether it's a fix and flip, BRRRR, small multifamily acquisition, or business purchase.
Related Reading
This article is for educational purposes only and isn't financial, legal, tax, or investment advice. Credit and financing outcomes depend on your own situation. Talk to a licensed financial professional before making funding decisions for your business.