
Cash-Out Refinance vs HELOC for Investment Property: Which Is Better for Real Estate Investors?

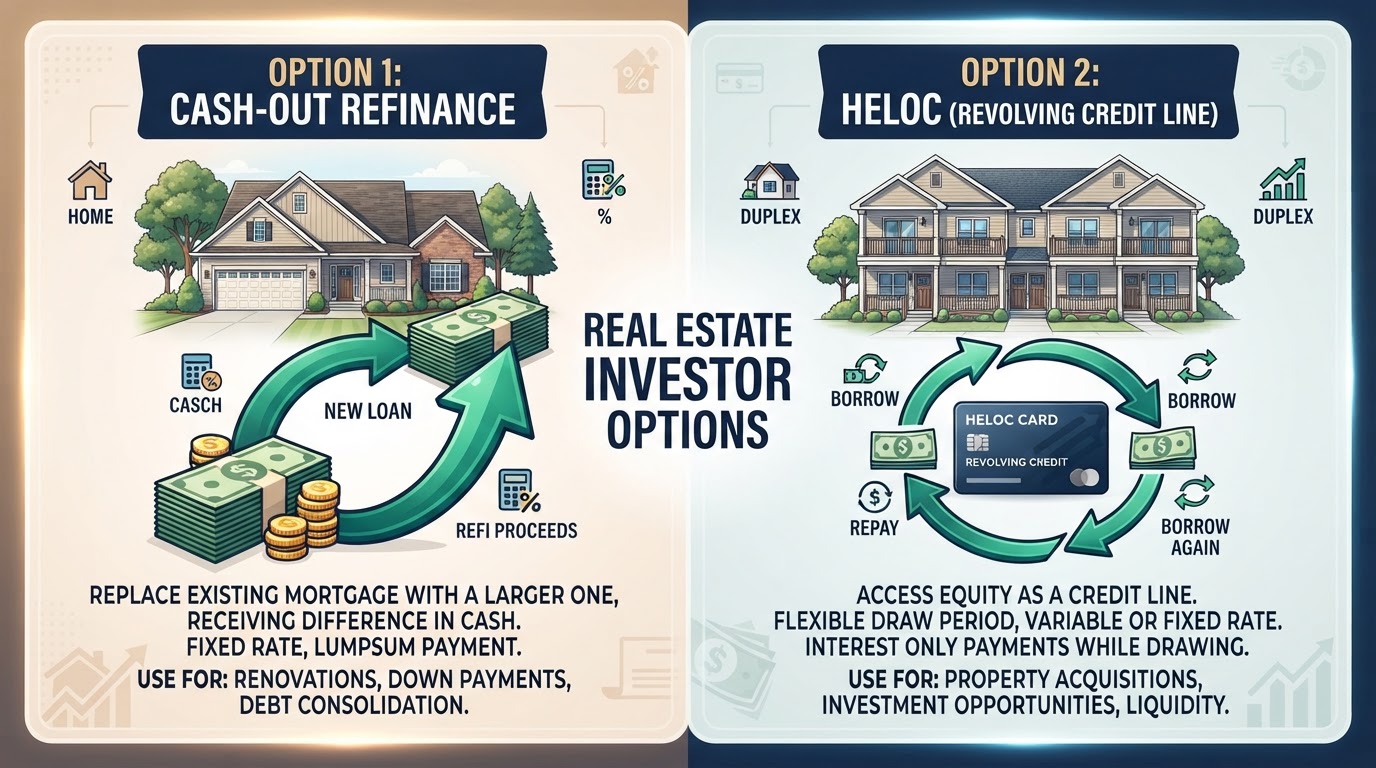
Cash-Out Refinance vs HELOC for Investment Property: Which Is Better for Real Estate Investors?
If you're sitting on equity in a rental property and trying to decide between pulling it out via a cash-out refinance or tapping it through a HELOC, the answer depends on your current mortgage terms, how you plan to deploy the capital, and how many deals you're running at once. Both tools unlock equity, but they work differently, cost differently, and qualify differently-especially on non-owner-occupied properties where lender appetite is far more restrictive than on a primary home.
Cash-Out Refinance vs HELOC for Investment Properties: The Short Answer
For most small-to-mid-size real estate investors who need a large, predictable amount of capital for a clear purpose-buying another rental, completing a BRRRR rehab, or exiting hard money-a cash-out refinance on an investment property is typically the stronger move. You get a single lump sum at closing, a fixed interest rate, and predictable monthly payment that simplifies cash-flow planning across your portfolio.
That verdict flips when you already have a historically low existing mortgage rate you don't want to give up, or when you need flexible, reusable capital across multiple deals over time. In that scenario, a HELOC-if you can find a lender willing to offer one on a rental-preserves your first mortgage and gives you a revolving line of credit you can draw from repeatedly.
Here's the catch most investors underestimate: even after maximizing either tool, there's almost always a funding gap. Down payments on the next acquisition, closing costs, rehab overages, and working capital for holding costs don't disappear just because you tapped equity. That's where Gap Funded's capital-stacking approach comes in-combining unsecured term loans, 0% business credit card stacking, and business lines of credit to cover what equity alone can't, without placing liens on your deal property.
The bottom line: choose a cash-out refi when you want maximum one-time leverage with rate stability; choose an investment HELOC when preserving a low first mortgage and deal-flow flexibility matter more; and layer in gap funding when either tool alone leaves money on the table.
What Is a Cash-Out Refinance on an Investment Property?
A cash-out refinance replaces your existing mortgage with a larger loan and delivers the difference as cash at closing. On an investment property-whether it's a single-family rental, a duplex in a BRRRR cycle, or a short-term rental-this is one of the most common ways investors recycle equity into their next deal.
For non-owner-occupied properties in 2025–2026, underwriting is tighter than on a primary home. Investment properties face stricter lending requirements compared to primary residences: stricter limits on loan-to-value ratios usually apply, with most lenders capping at 70–75% LTV for single-unit rentals and sometimes lower for multi-unit. Cash-out refinancing typically requires a home appraisal, a credit score review, and proof of income or verified rent rolls. DSCR lenders also impose minimum debt service coverage ratios (typically 1.1–1.25) and often require 3–6 months of title seasoning before approving a cash out.
Investors commonly use a cash-out refi to acquire additional rentals, fund rehab on BRRRR deals, pay off higher interest rate hard money or bridge loans, or pursue debt consolidation on business obligations. Rates carry a premium over primary-residence equivalents-roughly 7.25%–8.00% fixed for solid credit profiles in mid-2026, with DSCR ARM products sometimes lower in the 5.25%–6.50% range depending on leverage and property cash flow.
Cash-out refinancing provides a lump sum of cash at closing, and funds from cash-out refinancing can be used for investments, home improvements, or consolidating debt. However, using a cash-out refinance may reset your mortgage term and extend your repayment period-something to weigh carefully if your original mortgage was already years into amortization.
What Is a HELOC on an Investment Property?
A HELOC on an investment property is a revolving line of credit secured by the equity in your rental or STR, typically structured as a second loan that keeps your first mortgage intact. Unlike a cash-out refi, a HELOC doesn't touch your primary mortgage-it sits behind it as a junior lien.
The standard structure includes a draw period of 5 to 10 years during which you can borrow and repay repeatedly, followed by a repayment period of 10–20 years where the balance amortizes. You only pay interest on the amount drawn from a HELOC, not the full credit limit, which makes it efficient for investors who need capital intermittently rather than all at once.
The challenge: investment property HELOCs are rare. According to HMDA data, only about 27,000 investment-property HELOCs were originated in 2025 out of roughly 1.15 million total HELOCs-just 2.3% of the market. Most lenders either don't offer them or impose combined loan to value caps of 65–75%, credit score minimums of 700+, and strict rental income documentation where only 75–80% of gross rent is counted.
HELOCs often have variable interest rates that can fluctuate based on the prime rate or SOFR plus a margin. Median note rates for investment HELOCs ran approximately 8.5% in 2025-about 1 percentage point above owner-occupied equivalents. That said, for investors who want flexible capital for rehab budgets across multiple projects, earnest money deposits, or funding the launch of an Airbnb property, this equity line of credit can be a powerful tool.
Many investors instead use a HELOC on their primary home to fund investment deals, sometimes pairing it with gap funding tools for maximum reach. You can estimate your available equity using a HELOC calculator to see what's realistic before approaching lenders.
Cash-Out Refinance vs HELOC for Investment Property: How They Compare at a Glance
Here's a decision-focused snapshot of the key differences between these two tools when applied specifically to non-owner-occupied rental and investment properties.
| Factor | Cash-Out Refinance | Investment Property HELOC |
|---|---|---|
| Best for | Investors needing a large, one-time lump sum for acquisitions, major rehab, or debt payoff | Active investors wanting reusable, flexible capital across multiple deals |
| Typical Max LTV / CLTV | 70–75% for 1-unit investment; lower for multi-unit | 65–75% combined; median CLTV ~63.6%; rarely above 80% |
| Rate Type | Primarily fixed interest rate; some DSCR ARMs available | Variable interest rates tied to Prime/SOFR + margin |
| 2025–2026 Rate Range | ~7.25%–8.00% fixed (strong credit); ARMs 5.25%–6.50% | ~8.5% average; ranges from 8%–10%+ for riskier profiles |
| Impact on Existing Mortgage | Replaces your existing mortgage entirely | Keeps first mortgage intact; adds a second loan |
| Access to Funds | Single lump sum at closing | Revolving line with additional draws as needed |
| Upfront Costs | Closing costs of 2–5% of the new loan amount, plus appraisal and title | Lower upfront; may include annual fees, draw fees, minimum thresholds |
| Risk Profile | Higher total debt load, fixed payments; risk if giving up low rate | Payment shock when draw period ends; variable rate exposure |
The pattern is clear: a cash-out refinance delivers bigger, more stable capital in one event, while an investment HELOC offers smaller but reusable flexibility-if you can find a lender willing to offer one.
Total Leverage & Access to Capital
Maximum usable capital determines how fast you can scale. Whether you're acquiring your third rental, cycling through BRRRR deals, or pivoting to short-term rentals, the total funds you can access from equity directly shapes your deal velocity.
Cash-out refinance wins on raw one-time leverage. On a $400,000 investment property with a $200,000 current loan balance, a 75% LTV cash-out refi produces a new loan amount of $300,000-netting you roughly $100,000 in cash after paying off the existing mortgage. Most lenders allow borrowing up to 80% of home equity on owner-occupied properties, but investment properties typically cap at 70–75%. In 2025, about 99,035 conventional cash-out investment refinances totaled approximately $33.1 billion in volume, with a median CLTV around 70%.
Investment HELOC provides less upfront capital but greater long-term reusability. On that same $400,000 property with a $200,000 first mortgage, a HELOC might allow draws of $70,000–$75,000 to maintain a 70–75% combined LTV. A HELOC allows borrowing against home equity up to 85% in some owner-occupied scenarios, but investment property CLTVs are far more conservative-only about 5.4% of investment HELOCs exceed 80% CLTV. However, a HELOC provides a revolving line of credit based on home equity, meaning you can draw, repay, and draw again across multiple deals without needing a new closing each time. Average line sizes for investment HELOCs are substantial-about $384,000 per line versus $146,000 for owner-occupied-indicating that when these lines are approved, the properties behind them carry significant available equity.
Winner: Cash-Out Refinance for maximum one-time leverage; HELOC for long-term reusable capital. If you need the biggest single check to close a deal or retire hard money, the cash-out refi delivers more. If you're running 2–4 deals per year and need to recycle equity across them, the HELOC's revolving structure earns its keep-assuming you can qualify.
Cost, Rates & Payment Stability
For cash-flow-sensitive investors managing debt to income ratio thresholds, vacancy risk, and DSCR coverage, how much you pay in interest-and how predictable that payment stays-can make or break a deal's profitability.
Cash-out refinance typically locks in a fixed interest rate. In mid-2026, investment property cash-out refi rates sit in the 7.25%–8.00% range for borrowers with solid credit (680–720+), carrying a 50–100 basis point premium over owner-occupied equivalents. Cash-out refinances typically have fixed interest rates, giving you a single monthly payment that doesn't change with market conditions. Most cash-out refinances involve higher closing costs compared to other lending options-closing costs for cash-out refinancing range from 2% to 5% of the loan amount, covering appraisal, title, origination, and sometimes discount points. Cash-out refinancing usually incurs closing costs of 2-5% of the loan, which on a $300,000 loan means $6,000–$15,000 out of your proceeds.
Investment HELOC pricing is variable and volatile. With a marketplace average of 8.5% in 2025 and rates tied to the prime rate plus a margin, a 1–2% rate increase on a $100,000 draw could add $85–$165 per month to your costs. HELOCs often have variable interest rates that can fluctuate, creating payment uncertainty that's particularly dangerous when you're covering holding costs on a property that hasn't stabilized. Upfront costs are lower-fewer closing costs, no full origination-but annual fees and draw fees can accumulate over the life of the line.
The critical factor many borrowers overlook: if your current interest rate on an existing mortgage is significantly below today's market (say 4.5% from 2021), a cash-out refinance replaces that rate with a 7.5%+ rate on the entire balance-not just the cash-out portion. In that scenario, paying a higher variable rate on a smaller HELOC draw can make more financial sense than permanently giving up a below-market first mortgage.
Winner: Cash-Out Refinance for payment stability and budgeting simplicity. The trade-off: HELOCs cost less upfront and preserve a favorable existing mortgage rate, which matters enormously if your original mortgage was locked in during the low-rate era.
Flexibility for Deals, Rehab & Future Strategy
Active investors doing BRRRR, fix-and-flip, or launching short-term rentals need capital that adapts to shifting budgets, timelines, and opportunities. Flexibility isn't a luxury-it's how you avoid leaving deals on the table.
Cash-out refinance delivers a locked loan amount at closing. There are no additional draws, no revolving feature. If you need more capital later, you're looking at another full refinance with new closing costs, a new appraisal, and underwriting approval from scratch. This works perfectly when you know exactly what you need: a $150,000 lump sum to acquire and stabilize a rental, or $80,000 to complete a defined rehab scope. One closing, one check, one plan.
HELOC shines when your capital needs are spread across multiple projects or uncertain in timing. Consider an investor who needs $40,000 for rehab across three separate projects over 18 months: draw $15,000 for Project A, repay as rent stabilizes, draw $12,000 for Project B, repay, draw $13,000 for Project C. That revolving line structure eliminates the need for three separate financing events. It's also ideal for time-sensitive moves like wiring earnest money deposits within 48 hours or covering option fees on off-market deals.
Concrete example: An STR investor launching two new Airbnb units needs $25,000 for furnishing, photography, and marketing for Unit 1, then $20,000 for Unit 2 three months later. A HELOC lets them fund both from the same line of credit without a second closing. A cash-out refi would require pulling the full $45,000+ upfront and sitting on idle capital.
Winner: HELOC for ongoing flexibility across multiple deals; Cash-Out Refi for locked-in, single-project funding. The trade-off: a HELOC's flexibility comes with variable rate risk and the challenge of actually finding a lender willing to extend one on an investment property.
Qualification, Risk & Lender Appetite for Investment Properties
Lender appetite for investment property equity products is fundamentally different from primary-residence lending-and has been tightening since 2020.
Cash-out refinance qualification requires minimum FICO scores of 660–680 (with better pricing at 700+), DSCR thresholds of 1.1–1.25, verified rent rolls or lease agreements, and property seasoning of 3–6 months. A credit score review is necessary for cash-out refinancing, and proof of income is required. Denial rates climb sharply as investors push leverage higher: applications at 70–75% LTV face roughly 20% denial rates, jumping to approximately 38% at 75–80% LTV. Despite these hurdles, many borrowers can qualify with adequate documentation and equity.
Investment HELOC qualification is tighter still-and availability is the real bottleneck. Qualifying for a HELOC on an investment property often requires higher credit scores and lower LTV thresholds than on primary residences, with many lenders requiring 700+ FICO. Only a handful of national and regional institutions-TD Bank, Fifth Third, PenFed, Figure, and select credit unions-actively offer them, often case-by-case. Some restrict property types entirely, excluding rural properties, STRs, or anything above four units. Lenders frequently discount rental income to 75–80% of gross to account for vacancy.
On risk: both are credit secured obligations with serious default consequences. A cash-out refi carries the risk of higher total debt load and the permanent cost of giving up a lower interest rate. A HELOC introduces payment shock when the draw period ends and the balance begins amortizing-or when variable interest rates spike. HELOCs may have looser qualification terms for average credit on primary residences, but on investment properties, the opposite is often true.
Winner: Cash-Out Refinance for broader availability and more predictable qualification pathways. The HELOC wins for investors with exceptional credit and substantial equity who want to preserve their existing mortgage rate-but finding a willing lender remains the biggest obstacle.
How Cash-Out Refi and HELOC Create a Funding Gap for Investors
Even after maximizing equity through a cash-out refi or HELOC, most investors still face a funding gap-the difference between what equity release provides and what the deal actually costs. This is especially true in the 2025–2026 environment of elevated construction costs, tight LTV caps, and lender reserve requirements.
Common gaps include:
- Down payments: DSCR and conventional lenders typically require 20–25% down on new rental acquisitions, which may exceed your cash-out proceeds
- Closing costs and points: Appraisal, title, origination, and lender-required reserves can consume several thousand dollars beyond the deal's equity component
- Rehab overages: Materials inflation, contractor delays, and scope creep frequently push budgets 10–20% beyond initial estimates
- Holding costs and operating reserves: Vacancy periods, property taxes, insurance, and maintenance between acquisition and stabilization
- Earnest money deposits: Competitive markets demand fast EMD wires-often within days, not the weeks a refinance takes
- STR launch costs: Furnishing, photography, marketing, and staging for short-term rental properties require significant expenses before the first booking
Here's how this plays out in practice: an investor owns a $400,000 rental with a $200,000 balance. A cash-out refi at 75% LTV nets approximately $100,000 after payoff and closing costs. But the next BRRRR deal requires $80,000 for a down payment, $50,000 for rehab, $8,000 for closing costs, and $10,000 for reserves-a total of $148,000. That's a $48,000 gap that equity alone can't cover.
How Gap Funded Closes That Gap (Beyond Cash-Out Refi & HELOC)
Gap Funded is a capital-stacking specialist that helps real estate investors and small business buyers cover exactly what cash-out refinance and HELOC proceeds leave behind-without giving up equity in the deal or placing liens on the investment property itself.
The tools that pair with a cash-out refi or HELOC, deployed in a specific order that matters:
Unsecured personal term loans come first. These fixed-rate loans (typically 1–7 year terms) cover down payments, closing costs, and rehab budgets without requiring a lien on the deal property. Funding can happen in 24–72 hours-critical for time-sensitive earnest money deposits. No collateral means your title stays clean for future refinancing.
0% business credit card stacking layers on next. By strategically securing multiple business credit cards with 0% intro APR periods of 12–21 months, investors can fund materials, contractor draws, STR furnishing, and marketing at zero interest during the ramp-up phase. This is particularly effective for major expenses like full property renovations or Airbnb launches where you need to spend now and repay once cash flow stabilizes.
Business lines of credit and working capital fill the recurring needs-holding costs, emergencies, and rolling deal flow. These pair well alongside DSCR or hard money loans for investors executing multiple acquisitions per year.
Debt consolidation often comes before everything else if an investor is carrying high-interest consumer debt or merchant cash advances that are crushing their debt to income ratio. Reducing DTI first improves FICO, which in turn unlocks better loan terms on the primary financing and larger gap funding amounts.
Qualification is realistic: FICO 650+ for most unsecured tools, 700+ for the full stack including credit cards and HELOCs, with provable income or business revenue. No two-year-in-business requirement for personal-based funding. Compared to bringing in an equity partner or gator lender, Gap Funded's approach means no equity splits, no liens on the deal property, soft credit pulls to see options, and rapid execution.
Choosing between a cash-out refinance and a HELOC depends on individual capital needs and risk tolerance-but choosing Gap Funded's stacking approach means neither tool has to do all the heavy lifting alone.
Apply for a personalized capital-stack plan →
Cash-Out Refinance vs HELOC for Investment Properties: Which Should You Choose?
The right choice comes down to your current mortgage terms, credit profile, deal pipeline, and financial goals. Here's the decision framework:
- Choose a Cash-Out Refinance if:
- - You're okay replacing your existing mortgage and don't hold a historically low mortgage rate you'd lose
- - You need a large, predictable lump sum to execute a clear plan-buy 1–2 new rentals, complete a major rehab, or exit hard money
- - You prioritize fixed payments and simpler budgeting over revolving flexibility
- - You value a single monthly payment structure and want to lock in current loan terms for 15–30 years
- Choose an Investment HELOC if:
- - Your current mortgage rate is significantly below today's market and you don't want to disturb it
- - You value a reusable line to fund multiple deals, EMDs, smaller rehabs, and rolling opportunities
- - You're comfortable managing variable interest rates and potential payment increases during the draw period
- - You have strong credit (700+) and significant home's equity to qualify with the limited lenders who offer these products
- Choose a Cash-Out Refi or HELOC + Gap Funding if:
- - Your next deal's capital stack will still leave a gap after you tap equity-for down payment, rehab, closing costs, or reserves
- - You want to keep 100% of your equity instead of bringing in money partners
- - You want one coordinated plan to cover every layer of the deal without additional liens on the investment property
Tax treatment of borrowed funds varies based on their use and applicable tax rules, so consult a CPA on whether interest from either tool is tax deductible in your specific situation.
The "right" answer isn't universal-it depends on several factors unique to your portfolio, cash needs, and timeline. If you're not sure which combination makes financial sense for your next deal, get a tailored capital-stack strategy at Gap Funded.
Frequently Asked Questions About Cash-Out Refi vs HELOC for Investment Properties
Can I Get a HELOC on a Rental or Airbnb Property, or Only on My Primary Home?
Some banks and credit unions do offer HELOCs on investment properties, but availability is far more limited than for primary residences. In 2025, only about 27,000 investment-property HELOCs were originated versus over 1.1 million for owner-occupied homes. Expect lower combined loan to value caps (65–75%), higher credit score minimums (often 700+), and stricter income documentation where lenders discount rent by 20–25% for vacancy assumptions. Many investors instead use a HELOC on their primary home and supplement with Gap Funded tools to bridge the remaining gap.
Is a Cash-Out Refinance on an Investment Property Harder to Qualify for Than on a Primary Home?
Yes. Stricter limits on loan-to-value ratios usually apply to cash-out refinancing for investment properties-typically maxing at 75% LTV versus 80% for owner-occupied. You can typically borrow up to 80% of your home's equity on a primary residence, but investment properties require documented DSCR (minimum 1.1–1.25), FICO of 680+, verified rent rolls, and 3–6 month seasoning. Rates also carry a 50–100 basis point premium. Strong rental documentation and clean credit improve both pricing and underwriting approval odds significantly.
Can I Use Equity from One Investment Property to Buy Another?
Yes-both tools enable this. A cash-out refinance pulls a new loan amount larger than your current loan balance, handing you the difference to use as a down payment on the next acquisition. A HELOC lets you draw funds for the down payment and closing costs while keeping your first mortgage intact. Some lenders scrutinize borrowed funds used for down payments, which is where Gap Funded's unsecured term loans and credit card stacking provide an alternative funding path that doesn't raise lender red flags. Always stress-test your portfolio for vacancies and rate changes before layering additional debt-overleveraging is the fastest way to turn equity into liability.
Can I Have Both a Cash-Out Refinance and a HELOC on the Same Property?
In theory, yes-if the combined loan to value fits lender guidelines after the refi. In practice, most investors refinance first, build equity through appreciation or improvements, and then seek a home equity line as a second loan later. The risk of layering multiple secured debts on one property is real: if values decline, you're underwater on both. An alternative is supplementing your primary financing with unsecured gap funding that places no new lien on the property-preserving your options for future refinancing and keeping your title clean.
How Does Gap Funding Work Alongside a Cash-Out Refi or HELOC?
Gap Funded's tools are typically unsecured and do not require a lien on the investment property you're buying or refinancing. A practical stack might look like: DSCR loan covers 75% of acquisition → cash-out refi funds from another property cover the down payment → Gap Funded unsecured term loan covers closing costs and reserves → 0% business credit cards cover rehab materials and furnishings. The order matters because each layer is designed to complement the others without competing for the same collateral. Qualification starts at FICO 650+, with stronger stacks available at 700+. Cash-out refinancing can be used for home improvements or debt consolidation, while gap funding handles the pieces equity can't reach.
Related Reading
This article is for educational purposes only and isn't financial, legal, tax, or investment advice. Credit and financing outcomes depend on your own situation. Talk to a licensed financial professional before making funding decisions for your business.